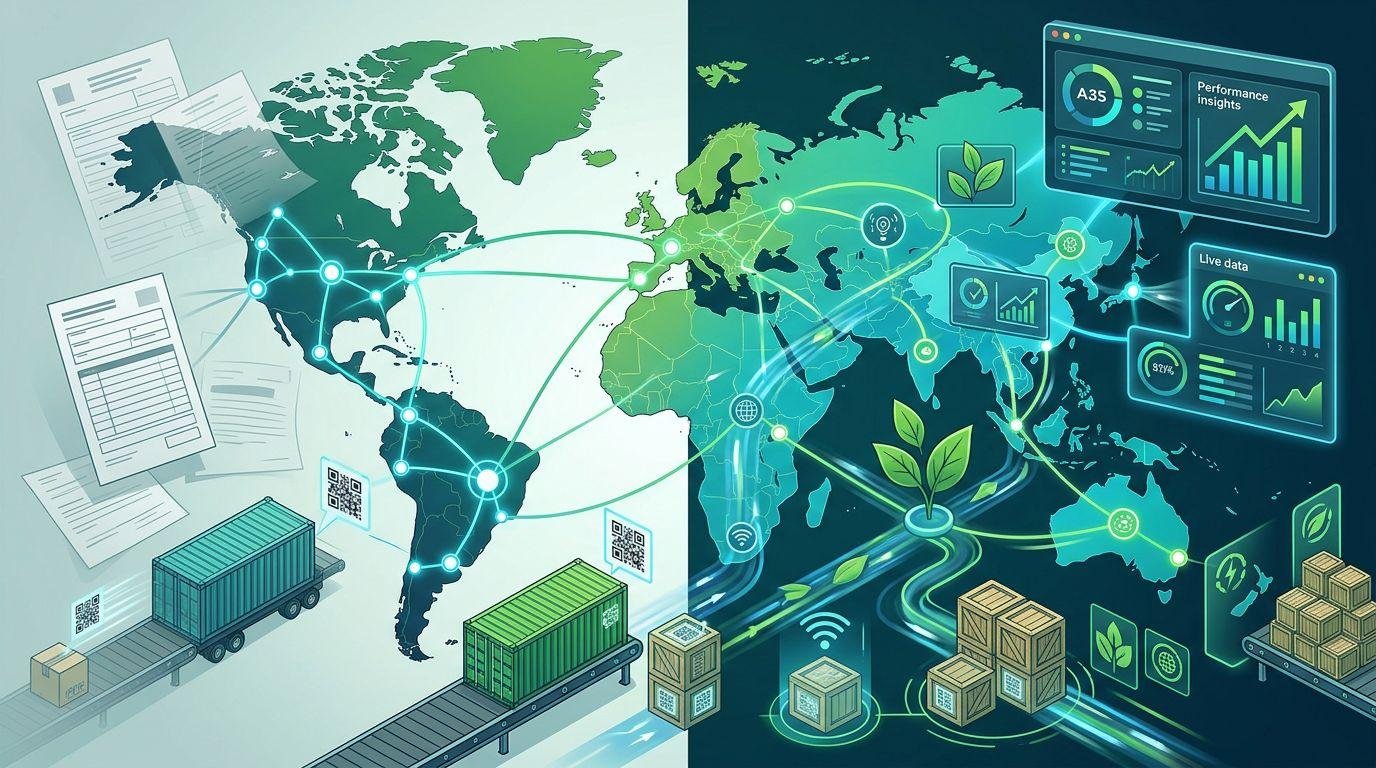
Most companies still struggle to trace the environmental footprint of their operations with the level of precision now expected by regulators, customers and investors. The problem is less about how sustainability results are presented than about the quality of the underlying data. In many organisations, ESG reporting has become more polished at board level while leaving procurement and product teams without a clear view of how individual sourcing choices affect emissions, resource use...
Continue Reading This Article
Enjoy this article as well as all of our content, including reports, news, tips and more.
By registering or signing into your SRM Today account, you agree to SRM Today's Terms of Use and consent to the processing of your personal information as described in our Privacy Policy.
and wider environmental impact.
That mismatch is increasingly difficult to ignore. McKinsey has said only 30% of companies can see beyond their direct suppliers, leaving most businesses with limited visibility into the upstream tiers where much of their risk and environmental impact sit. Other supply-chain analysis cited in recent industry commentary suggests the problem may be even broader, with large numbers of companies and suppliers lacking systems capable of monitoring sustainability performance deeper in the network. However framed, the message is the same: transparency often stops far earlier than modern ESG expectations do.
The consequences are both practical and commercial. According to packaging sector commentary, sustainability-marketed products already account for a meaningful share of consumer goods sales in the United States, while a sizeable portion of corporate revenue is expected to align with the climate transition. That means ESG is no longer just a disclosure exercise. It has become part of how brands win shelf space, secure B2B contracts and position themselves against competitors. In categories where products are otherwise similar, the ability to substantiate a lower product carbon footprint can influence selection even when it does not command a premium price.
The deeper issue is structural. ESG programmes have traditionally been built around retrospective reporting, with data gathered from separate functions and stitched together manually or semi-manually to satisfy disclosure frameworks. That approach can support baseline compliance, but it does little to guide decisions in real time. In global supply chains, where materials, logistics and manufacturing are spread across multiple tiers, the use of averages and estimates can blur the differences between suppliers and conceal the origin of the highest-impact inputs.
This is where AI-driven data systems are starting to change the conversation. Rather than treating sustainability information as something to assemble after the fact, companies are beginning to embed environmental metrics into the master data for ingredients, materials and production pathways. In sectors such as food and drink, where supply chains are highly distributed and supplier data can vary in format and frequency, that shift is particularly significant. Industry platforms including IntegrityNext, Deeplai, Reput and Blockforce all point to a broader move towards integrating compliance, traceability and sustainability intelligence into operational systems rather than leaving them in separate reporting silos.
The attraction is not only better reporting but stronger decision-making. If emissions, cost, quality and availability can be assessed together at the point of procurement or formulation, businesses are better placed to make trade-offs before commitments are locked in. In practice, that could mean replacing static estimates with supplier-specific information, linking ingredient-level data to environmental datasets and using automated tools to flag risks earlier in the sourcing process. The aim is to move from broad sustainability claims to evidence that can be traced back through the supply chain.
Regulation is likely to reinforce that shift. The European Union’s Corporate Sustainability Reporting Directive is raising the bar on the quality and traceability of corporate disclosures, while expectations in the United States continue to evolve. At the same time, rules around green claims and product-level environmental information are putting fresh pressure on companies to support what they say with verifiable data. In that environment, high-level commitments will not be enough on their own. Buyers, regulators and investors are increasingly looking for proof rooted in supply-chain evidence rather than industry averages.
For businesses trying to stay ahead, the next stage of ESG maturity is less about preparing another report and more about embedding environmental intelligence into everyday operations. That means integrating ESG data into core business systems, extending visibility beyond Tier 1 and Tier 2 suppliers, and making impact information available during design and formulation, not after products have already been developed. Companies that can do that will be better placed to manage risk, strengthen credibility and compete in markets where sustainability is becoming a basic requirement rather than a differentiator.
Source: Noah Wire Services